XactFlex
A small-business line of credit designed from nothing, and the payment flow that came after it, built on the same three moves: slider as input, table as receipt, hard review before commit.
- CLIENT
- XactFlex
- YEAR
- 2019–2022
- ROLE
- Design Lead
- DURATION
- 2019–2022 · ongoing client work
- TEAM
- Designer (me) · engineering partner · risk and compliance reviewer
- STACK
- Adobe XD · Figma
Tap any tab: Account / Payments / Preferences / Draw. The draw slider re-computes the cash advance fee and deposit live.
A playable rebuild of the XactFlex payment surface, redesigned with a 2026 product sensibility. Pick a payment type, set an amount, choose a date on the calendar, authorize, and submit. Use the back arrow at any time, or hit reset to start over.
Where should we pull from?
This is the bank account associated with your loan. To change it, contact Customer Service.
Need to change accounts? Call Customer Service before scheduling a payment.
The Situation We Walked Into
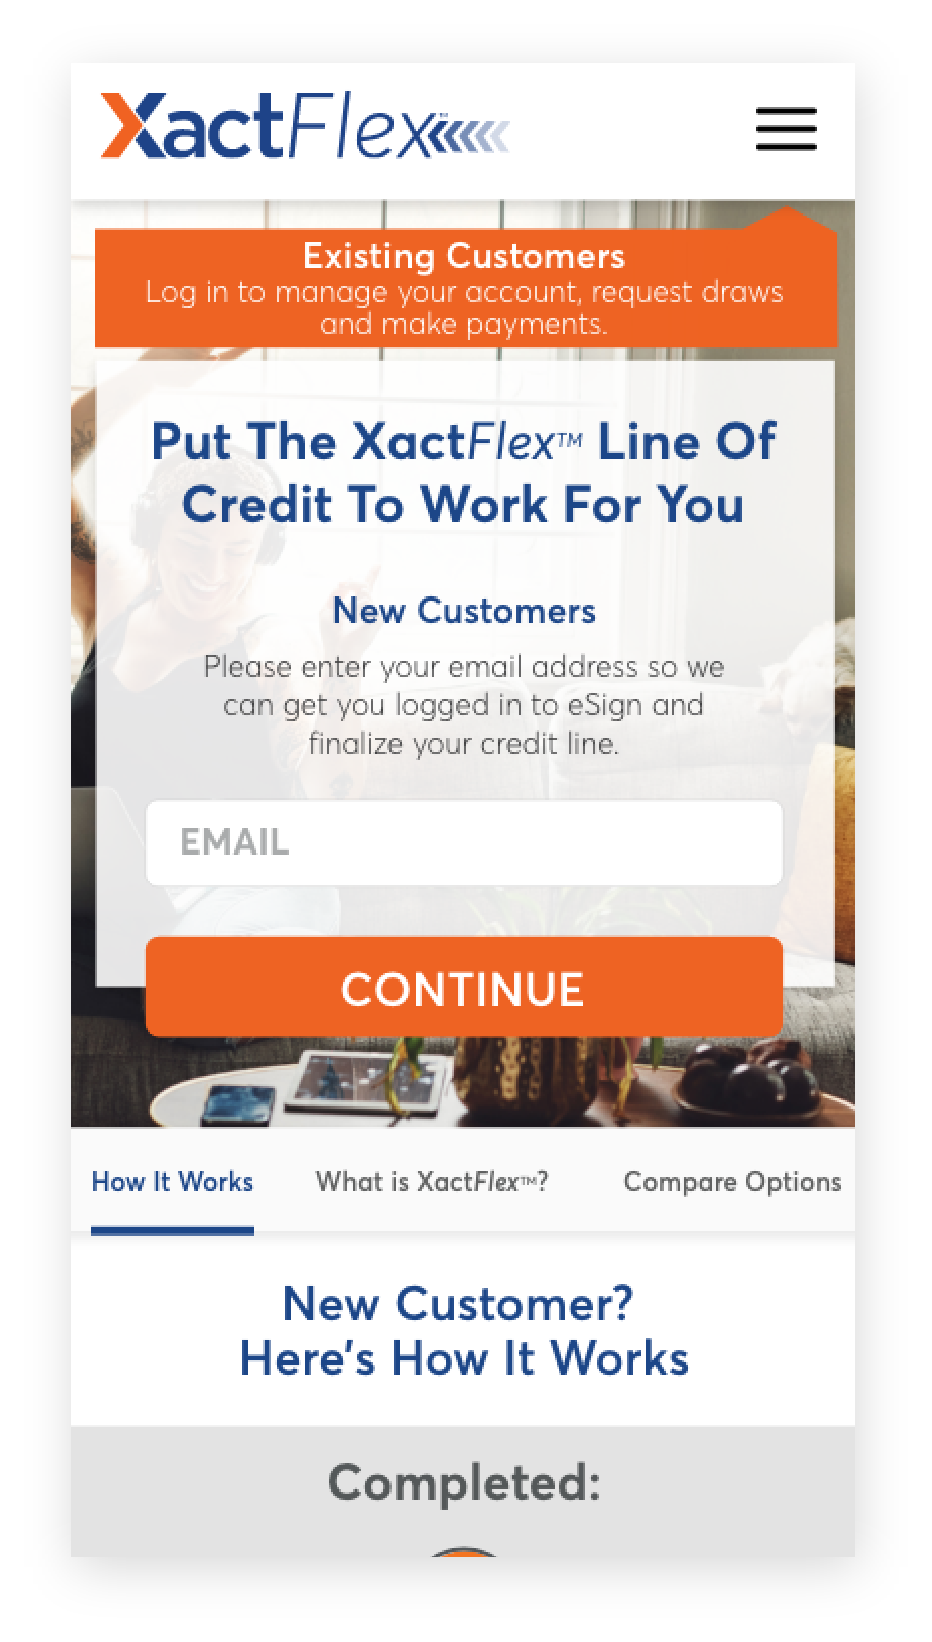
XactFlex was launching a small-business line of credit. Customers would draw against a revolving balance and repay on a schedule. There was no existing flow to improve. The whole experience had to be designed from the product's anchors up: a balance, a limit, and the option to draw.
The work ran on two tracks. First the launch: the account surface, the draw flow, and the review screen that commits real money. Then, after launch, the operational payment flow. Customers were making recurring payments through a multi-page legacy wizard that gave every decision the same weight, and they were either abandoning it or calling support to ask whether the payment had gone through.
Both tracks shipped on one vocabulary. The slider-and-table pattern from the draw flow returns in the payment surface as quick-pick choices over a live amount. The hard review before commit is the same shape in both flows: different fields, same gesture, same reason.
The Box We Had to Work Inside
- 01MOBILE FIRST, ON BOTH SURFACES
Most customers reached XactFlex from a phone. Every flow was designed for one thumb and a vertical scroll, then adapted for desktop, never the other way around.
- 02LIVE RECOMPUTE UNDER 60 MS
Every tick of the draw slider recomputes the cash advance fee, the repayment plan, and the first payment date. The budget was 60 milliseconds per tick. Slower than that, the numbers lag the thumb and the customer stops trusting them.
- 03A NO-JAVASCRIPT PATH ON THE COMMIT STEP
The payment flow had to complete as a plain form submission if JavaScript failed or a screen reader was driving. Progressive enhancement on the one step that moves money.
- 04DISCLOSURES INLINE, NOT BEHIND A TAP
Cash advance fee, APR, repayment terms. These are regulatory disclosures, and they had to be visible during the decision, not in a Terms modal after it. Compliance reviewed the inline placement.
- 05ONE VOCABULARY ACROSS THE PRODUCT
The launch surfaces and the later payment surface had to read as one app, not two flows stapled together. Same palette, same density, same primitive interactions.
The Calls We Made, with Rationale
- 01Slider as primary input, table as receipt
On the draw surface the slider is the input. Under it, a small table updates in place: cash advance fee, repayment plan, first payment date, total cost. The customer reads the consequence of the amount before committing to it. There is no type-a-number-then-discover-the-cost step, because the cost is on screen the whole time.
- 02Three surfaces, one question each
Both tracks compress to three surfaces. Draw: Account, a read-only summary with a utilization donut; Draw, the slider with its live table and inline disclosures; Review, the commit. Payment: Method, Type, Date, then Review. One question per surface. The legacy payment wizard asked all of them at once.
- 03A hard review with a two-action commit
Both flows end on a review screen that looks different from everything before it: different ground, larger type, the amount restated. Committing takes two deliberate actions, Authorize and then Submit. It read as redundant in design review. The drop in payment-status calls is the argument for it: two taps when real money is moving is cheap insurance.
- 04Quick-pick before custom entry
The payment Type step leads with Minimum, Payment Plus, and Pay-off as one-tap choices, with the numeric field below for anyone who needs a specific figure. The custom field stays in place as the fallback, not the front door.
- 05“Other Amount” explains itself
Other-amount payments do not apply toward the next scheduled payment, which is exactly the kind of distinction that generates a support call after the fact. The Other path carries an inline note saying so, where the customer is already reading, before they can submit and be surprised.
- 06A step banner as a reusable primitive
A thin persistent banner at the top of each flow shows 1 of 3, 2 of 3, 3 of 3, and tapping a step walks back without losing state. It got a name and a spec, and it ships on both the draw and the payment flows.
Artifacts and the Path
- 01PIN THE PRODUCT ANCHORS FIRST
Defined what the slider reads, what the table renders, and what the review restates before drawing anything. A revolving line of credit reduces to a balance, a limit, and the option to draw. Pinning that made the UI tractable.
- 02PROTOTYPE THE SLIDER
Built the slider behavior in Adobe XD with snapping increments and tuned the step until it matched the product's price points. Engineering took the spec, including the 60 millisecond recompute budget, into the build.
- 03REVIEW THE DISCLOSURES WITH COMPLIANCE
Walked the inline placement through compliance. It held because the disclosures are continuously visible during the decision rather than behind a tap. The full terms stay one expander away.
- 04AUDIT THE LEGACY PAYMENT WIZARD
Went through the legacy flow step by step and marked where customers were dropping or calling: amount entry, date selection, and an unlabeled “apply to” choice. Each had to land somewhere in the new flow or be cut on purpose.
- 05REUSE THE LAUNCH VOCABULARY
Took the slider-and-table pattern, the three-surface compression, and the two-action commit from the draw flow into the payment redesign. The surfaces read as one product because they are built from the same primitives.
What Shipped and What It Moved.
- FIG. 01SECONDS, END TO END~90 s0306090120~90s
to complete a draw decision end to end
- FIG. 02SUPPORT CALLS, INDEXED38%
fewer payment-status support calls after the new payment flow shipped
- FIG. 03PER SLIDER TICK60 ms025507510060 ms
recompute budget per slider tick, the constraint that made the live table feel immediate
- FIG. 04SURFACES SHIPPEDLandingAccountDrawPaymentPreferences5
mobile surfaces shipped: landing, account, draw, payment, preferences
The slider-and-table pattern shipped as the draw experience for the new line of credit, with the repayment plan recomputing live so the customer sees the cost before committing. The same slider ships on the desktop dashboard with the layout adjusted for width.
The three-step payment flow shipped and became the default payment path. The step banner and the two-action commit are now the model for any XactFlex surface where money posts.
The two numbers I cite are the ones that were measured: draw decision time and payment-status call volume. Everything else in this study is a design decision, not a result.
What I'd Do Again, What I Wouldn't
- Speed of feedback is part of the design
The 60 millisecond budget looked aggressive when we set it and cost engineering real work to debounce the live calculation correctly. It is the call that made the slider feel immediate. A slower version felt sluggish enough to make the numbers under it look untrustworthy, and a number you do not trust is not a disclosure.
- The redundancy is the point
The two-tap commit was the contested decision. On a review screen that already restates the whole payment, a second confirmation looks like friction. The support-call drop is the answer. Slowness at the moment money moves is what the gesture is for.
- What I would do next
A numpad fallback on the draw slider for customers who think in exact figures, and a closer look at the “Other Amount” rule, where an inline note is doing work the product model should probably do instead. Both are long-tail. The canonical flows hold.